Faites connaître cet article à vos amis:
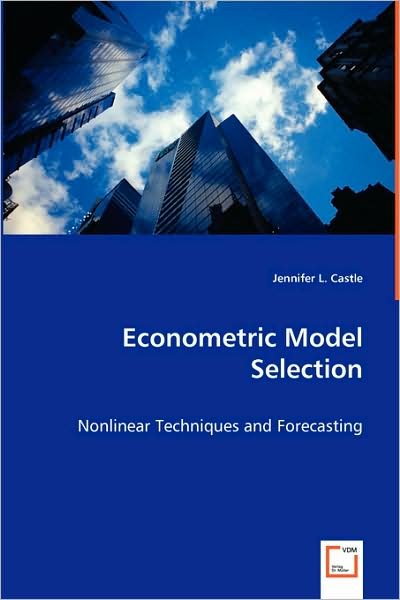
Econometric Model Selection: Nonlinear Techniques and Forecasting Jennifer L. Castle
Commandé depuis un entrepôt distant
Nos clients disent :
Econometric Model Selection: Nonlinear Techniques and Forecasting
Jennifer L. Castle
Selection and forecasting are integral to econometric modelling but a unified treatment is rarely considered. This book addresses both issues, with an application to UK inflation. The theme of model selection underpins all chapters of the book. The development of any econometric model requires model selection rules because economic processes are extremely complex and the underlying data generating process is unknown. Furthermore, different model selection rules may be required for in-sample modelling and for forecasting, when the data generating process is evolutionary, non-stationary, and unknown to the econometrician. This book develops methods for selecting nonlinear models, proposing an easy to implement algorithm which circumvents identification problems, and builds equilibrium correction mechanisms of inflation to examine their forecast performance against robust devices. The book provides a comprehensive treatment of model selection, demonstrating that general-to-specific selection tools are integral to modelling and forecasting in a non-stationary world, and should be an invaluable read to those building econometric models for forecasting and policy evaluation.
| Médias | Livres Paperback Book (Livre avec couverture souple et dos collé) |
| Validé | 13 mai 2008 |
| ISBN13 | 9783639004588 |
| Éditeurs | VDM Verlag |
| Pages | 200 |
| Dimensions | 150 × 220 × 10 mm · 272 g |
| Langue et grammaire | Anglais |